#On the Men Who Count the Counting
"Every receipt is a confession, written by the collector in his own hand." (Maxim of the Tithes Discipline Office, unattributed and much copied)
The Audit Liaison is the officer of the Bureau of Tithes whose single duty is to count other people's counting. He collects nothing. He carries no folding scale into a tenement stairwell, he chalks no door, and so far as I can learn no widow has ever thrown a pot at one. His debtors are the Tithe Assessors, and what he collects from them is the discrepancy.
The Bureau says he exists to prevent theft. That is a kind way to put it. The Bureau has already worked out how much theft it can afford, and it keeps the figure in memoranda that circulate more freely than their seals would suggest: approximately seven percent of total collection. Below that line, prosecution costs more than the thing stolen. Above it, the Synod's confidence in its own ledgers begins to rot. The Liaison keeps theft under the line. He guards the Bureau's right to steal lawfully against the Assessor's habit of stealing for himself.
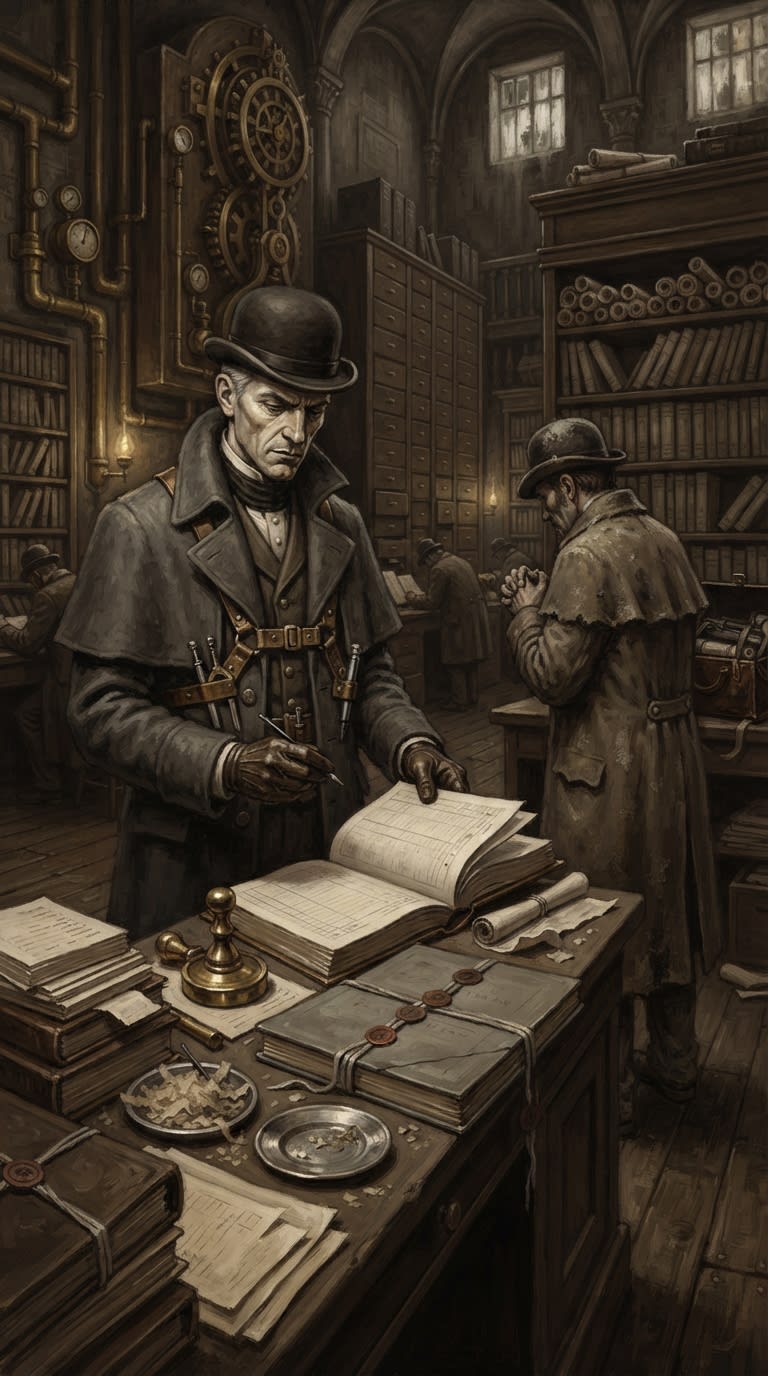
His place in the Bureau is awkward, and it was made that way on purpose. Each morning a Quota Captain counts the day's receipt blanks and enters the number in triplicate. The Liaison counts the triplicate. He reports upward to the Discipline Office of the Palatine Counting House in Strasbourg. He checks district rolls against the registers of the Bureau of Records. When a discrepancy smells of heresy instead of plain greed, he refers it to the Bureau of Purity. He does this as seldom as he can, because once Purity is invited into a ledger it never leaves.
Other Bureaus use the title. Records keeps Liaisons who confer with its Records Scribes in a room with one chair. This entry covers the Tithes office, the oldest by appetite if not by charter.
#On the Instruments
The Liaison's kit is smaller than the Assessor's and more feared.
First comes the blank tally. It sets blanks issued against counterfoils stamped and spoiled blanks returned, and the three numbers must agree. When they don't, there is no appeal, and under the Ledger Laws of A.S. 112 no excuse will be heard.
Second is the seal-wear gauge, a brass plate cut with graded impressions. An Assessor's seal wears at a known rate per thousand stampings. If a seal is too sharp for its route, it has stamped too little, and payments were taken without receipts. If it is too worn, it has stamped too much, and receipts were issued for payments that never reached the district stores.
Third is the duplicate household roll, drawn from Records and compared name by name with the Assessor's route ledger. It turns up the dead who still pay and the living who have stopped.
Fourth are the brine-stone scrapings. The Assessor's testing stone keeps the residue of everything pressed against it. The Liaison scrapes it and counts the rejections. Then he walks to the seizure yard to see whether the rejected salt arrived, or went back to market at full price.
Fifth is the exception ledger. Every exemption and every adjustment to the Burden Index has to be entered in it, sealed and justified. So does every debt forgiven on the Feast of Balanced Scales under the patronage of Saint Ysolt.
Last is the custody cord, a narrow grey seal-cord knotted around a seized ledger with each knot numbered. Once the Liaison ties it, the Assessor's books no longer belong to the Assessor.
#On the Ritual of Inspection
The Liaison arrives without warning. He comes at dawn before the blanks are issued, or at the end-of-day reconciliation when the Assessors come back smelling of brine and stairwells. The door is shut behind him and nobody leaves. The escort captain takes up his post inside the door. It is the first sign that the escort no longer works for them.
Blanks are counted first. A short weight can be blamed on grey salt, and a missing entry can be blamed on a dead clerk. A missing blank can't be blamed on anything.
Widow accounts always come next. Since Kaethus Brenn's memorandum of A.S. 138 and Directive 91-B the following year, the Widow's Pennies have been mandatory and universal, charged at a reduced rate. A reduced rate leaves a gap, and a hand fits in a gap. On the widow route, mercy and theft produce the same ledger. The Assessor who lets a widow keep her eleven pennies records a shortfall. So does the Assessor who keeps them himself, and both do it with the same honest face.
After the widows he turns to the Cradle Decree accounts. They have been active since A.S. 157 and are rich ground, because an unborn debtor can leave the roll for reasons no Assessor must explain in detail. When a projected infant due vanishes, the Liaison asks for the Records entry that accounts for it. If there is none, he writes the Assessor's name in the margin in rust-brown ink, the same ink the Assessor uses on doors.
#On the Frauds They Find
The Liaison knows the Assessor's standard frauds by their fingerprints.
A split due shows up as a gap between the counterfoil and the store. The arrears leash is harder to catch, because what gives it away is steadiness: a household exactly one payment behind for six years running. Real poverty is irregular, while a leash holds at the same length every month. The salt test shows in the scrapings, where there are too many rejections for the salt that reached the yard. It also shows at the seizure gate, where the fence wears better boots than his trade can pay for.
The Liaison also finds refinements. There are forged exemptions, sealed with instruments bought from seal-forgers who charge by the letter. There is Burden Index softening, which moves a patron's cousin to a gentler score, and its twin, hardening, which pushes a household up the Index so it is easier to leash. Then there is patron-protected mercy: an exemption recorded properly and sealed properly for a family whose eldest daughter keeps house for the District Assessor. The Liaison finds this last kind most often and reports it least, because patrons have patrons.
The rarest is the fictive district.
An earlier draft of this entry credited the Audit Liaisons with exposing the non-existent districts uncovered by the A.S. 194 audit.
The districts did not exist, and they passed audit every year. Every earlier certificate carries a Liaison's seal. The A.S. 194 audit was a Liaison audit of earlier Liaison audits, and it has been filed as a triumph of the office rather than an indictment of it. The Liaison responsible has been reassigned. His successor has certified that the reassignment took place.
#On Public Accounting
An Assessor whose theft is proved but is not systemic receives public accounting, on a market day in his own district. He stands at the licensed weighing stall with his ledger open, and the Liaison reads it aloud line by line: household, due, sum received, sum recorded. After each line the Assessor answers Received or Not received. When his answer and the counterfoil disagree, the Liaison says nothing and makes a mark. The district counts the marks.
The ledger is read in full. Every honest debt in the book goes out over the market along with the thief's frauds. The butcher hears what the chandler owes. The widow hears her own arrears read to her neighbours in the same even voice as the Assessor's crimes. One man is shamed and three hundred households are humbled, which the Bureau finds economical.
Demotion follows, to the worst routes or to trench camp dues, where the debtors carry rifles. When pressure rises, it falls on the unprotected first. Route dogs go before patron-linked senior men, runners before clerks, clerks before Captains. Everyone knows the order. It is the Bureau's real hierarchy. The one printed in the Field Manual is its liturgy.
#On Immurement and the Vaults
For systemic fraud the custody cord has one more use. The falsified ledgers go down through the eastern service door of the Palatine Counting House, and the Assessor goes with them. In the basement vaults the Immurement Masons close a niche behind the books he altered. The Liaison's part is shorter: he writes the closing balance and signs it. The Assessor's name stays on the audit schedule, because the schedule has no field for a man who has been walled in, and the Discipline Office has never asked for one.
#On Present Use
It is A.S. 201, and the Audit Liaisons are overworked. In A.S. 199 three Tithes Assessors were killed in the Rhineland, the first field deaths since the Grain Tithe Riots of A.S. 160. Frightened Assessors steal more, and fewer of them now cover more doors. Archbishop Salome Veyrault has held office since A.S. 189. Under her the Discipline Office holds that revenue is only as good as the belief that it was counted properly, and the Liaisons keep that belief intact.
Hence the office's most admirable perversion. The route ledger the Liaisons fear most is the one that comes back perfect. It means the Assessor has either stopped stealing, which the Bureau considers improbable, or learned to steal without leaving a trace, which it considers intolerable. Veteran Liaisons trust a ledger that sits comfortably in the low single figures and distrust one with nothing in it.